The short version
- Firmus Technologies is drastically reducing its valuation ahead of a planned stock market debut, with sources indicating the initial public offering could be abandoned entirely.
- The company’s worth surged from under $2 billion to nearly $44 billion in just over a year, driven by investments from major tech and finance firms despite limited operational infrastructure.
- Analysts warn that the high price tag relies on successful construction of unbuilt facilities and continued heavy spending by large technology clients, both of which face significant risks.
Firmus Technologies is facing a sharp correction in its market valuation just weeks before it was scheduled to launch what would have been the largest initial public offering in Australia since 1997. The company, which specializes in building and operating datacenters for artificial intelligence workloads, has abruptly withdrawn from a parliamentary inquiry on AI amid intense internal discussions about how to proceed. Sources indicate that the firm is either slashing its target price significantly or considering shelving the listing altogether due to a lack of investor enthusiasm at previous valuation levels.
The volatility in Firmus’s perceived worth has been extreme. Less than a year ago, the company was valued at approximately $1.85 billion when major investors, including chip manufacturer Nvidia and financial firms such as Blackstone, Jane Street, and Coatue, took equity stakes. Over the following months, successive rounds of capital raising pushed that figure to $15 billion roughly eight weeks ago. In a rapid escalation, the valuation climbed to nearly $44 billion just days before the anticipated listing. This trajectory has now reversed, with backers frantically attempting to find a price point that skeptical investors will accept.
Critics argue that the previous pricing was detached from financial reality. One investment manager described the earlier valuations as fanciful, noting that the company continues to lose hundreds of millions of dollars while its worth increased consistently every few months. The core issue for potential buyers is not whether the demand for AI infrastructure will persist, but whether the current price adequately accounts for the substantial operational hurdles Firmus must overcome to generate returns.
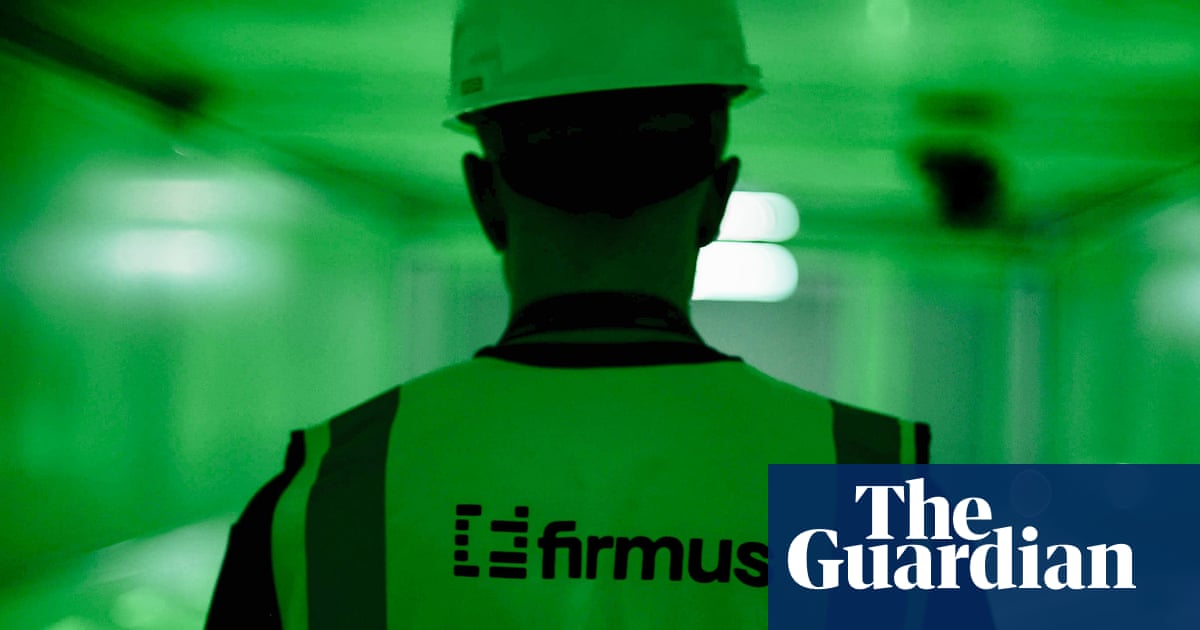
Firmus’s business model centers on constructing liquid-cooled facilities equipped with Nvidia graphics processing units to serve major technology companies. While it has secured contracts with prominent clients such as Meta, OpenAI, and Nvidia, the physical infrastructure supporting these agreements is largely nonexistent. According to Armina Rosenberg of Minotaur Capital, approximately 97 percent of the contracted revenue is tied to sites that have not yet been built. The company currently operates only two small facilities, with seven more under contract and four in the planning stages.
The high valuation assumes that Firmus can execute its construction pipeline flawlessly while securing necessary financing and maintaining client renewals. This plan faces external pressures, including growing community opposition to datacenter developments in regions like the United States and Australia. Although Firmus has focused its expansion efforts on Asia to avoid some of this local backlash, it still contends with significant challenges related to power availability and construction timelines in those markets.
Furthermore, the financial projections underpinning the $44 billion figure depend on sustained, heavy expenditure by hyperscale technology firms such as Microsoft, Google, and Meta. If these companies reduce their spending on AI infrastructure, third-party datacenter operators like Firmus could be among the first to experience a downturn. The market’s current optimism does not account for potential shifts in client behavior or broader economic constraints that might slow capital investment.
Market analysts have drawn parallels between Firmus’s situation and classic bubble dynamics. Lochlan Halloway, an analyst at Morningstar, suggested that sentiment around the company has entered a euphoric phase, characterized by excessive optimism rather than fundamental value. This does not imply the business lacks merit, but rather that investors may be paying a steep premium for future growth that is far from guaranteed. The risk lies in the gap between the price paid and the actual delivery of services.
Originally, Firmus planned to list on the Australian Securities Exchange on October 23 at a share price of $11. That figure is now subject to radical reduction or complete withdrawal. The uncertainty surrounding the listing highlights broader tensions in the AI infrastructure sector, where rapid valuation increases have outpaced physical development and profitability. Investors are increasingly cautious about committing capital to companies that promise future earnings based on unbuilt assets and unproven operational scales.
The situation serves as a cautionary tale for other startups seeking public listings in the current market environment. While the demand for AI computing power remains strong, the translation of that demand into sustainable corporate value is complex. Firmus’s struggle to maintain its valuation underscores the difficulty of balancing ambitious growth projections with the realities of construction delays, regulatory scrutiny, and fluctuating client spending patterns.
As the company navigates this critical juncture, the outcome will likely influence how investors view similar infrastructure plays in the coming months. Whether Firmus proceeds with a reduced valuation or cancels the offering entirely, the episode illustrates the fragility of high-growth narratives when confronted with immediate financial and operational constraints. The market’s reaction to this adjustment will provide insight into broader investor sentiment regarding AI-related investments.
Sources behind this briefing
Go to the original reporting
- The Guardian World↗Datacentre company Firmus’s high flying valuation may be coming back down to earth ahead of expected ASX debut