The short version
- The national debt has exceeded $40 trillion while the federal deficit remains near 6% of GDP, raising concerns about long-term fiscal sustainability.
- Treasury Secretary Scott Bessent is shifting toward short-term borrowing and bond buybacks, a move critics warn could undermine market confidence.
- Global interest rates are rising broadly, reducing the unique advantage previously held by US Treasury securities as safe-haven assets.
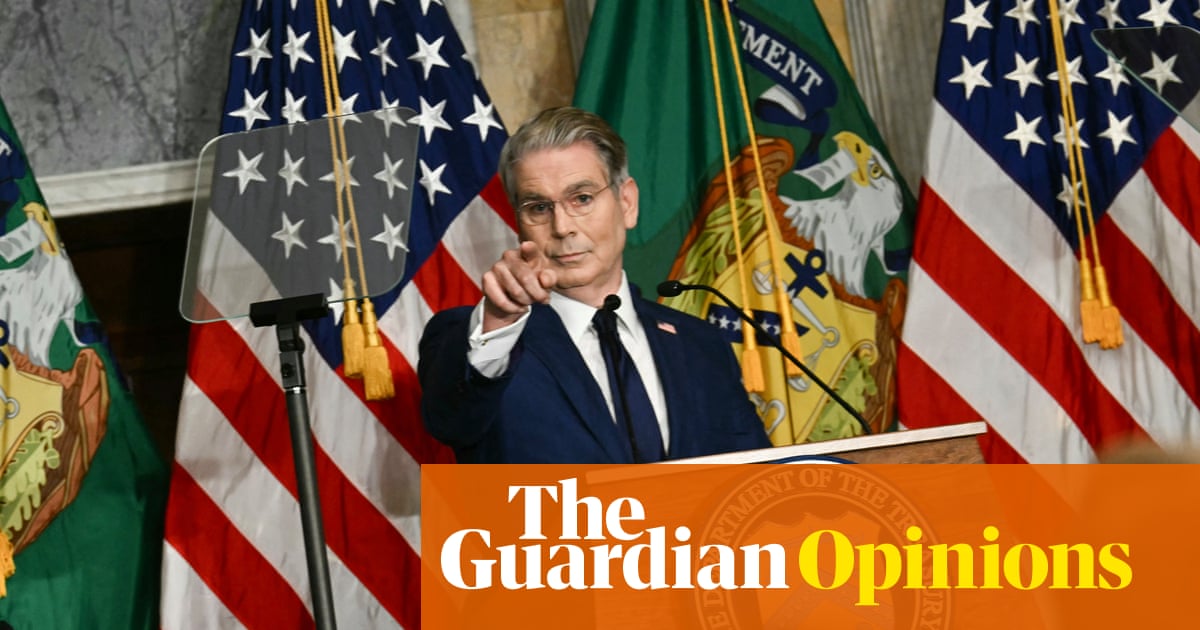
The United States federal debt has crossed the $40 trillion threshold, intensifying scrutiny of the administration’s fiscal strategy amid a persistent deficit running at approximately 6% of gross domestic product. This milestone has sparked debate within economic circles regarding the sustainability of current borrowing practices and the potential impact on global financial stability. While Treasury Secretary Scott Bessent has previously characterized concerns over the debt ceiling as insignificant, recent market dynamics suggest a more complex reality that challenges the administration’s optimistic growth projections.
Bessent’s central argument rests on the expectation that artificial intelligence-driven economic expansion will generate sufficient tax revenue to naturally reduce the deficit to a more manageable 3% of GDP without requiring immediate austerity measures. He has assured investors that the current surge in borrowing is temporary and that the United States will continue to attract global capital due to its unique position in the international financial system. However, this reliance on future technological gains faces skepticism from economists who note that taxing profits from automated systems may prove more difficult than traditional labor income.
Compounding these structural challenges is a broader shift in global interest rates. Long-term real interest rates are rising across advanced economies, indicating a normalization rather than a temporary aberration. This trend erodes the historical premium associated with US Treasury securities, which have long benefited from their status as a premier safe asset. As this advantage diminishes, the dollar’s dominance faces subtle but significant pressure, potentially accelerating a decline in its global market share that might otherwise have unfolded over several decades.
In response to these pressures, Bessent has begun altering the maturity structure of government debt, favoring short-term instruments over long-term bonds. This strategy involves promising to remove long-term obligations from the system and replace them with shorter-duration debt, a maneuver reminiscent of quantitative easing tactics employed by the Federal Reserve. While such approaches can be effective during periods of acute market panic when long-term rates are expected to fall quickly, there is little evidence that current bond markets are experiencing such distress.
Critics argue that this pivot toward short-term borrowing reflects an attempt to strong-arm the bond market rather than address underlying fiscal imbalances. By avoiding immediate spending cuts or tax increases, the administration risks undermining Bessent’s credibility as a stabilizing force within the Trump economic team. His previous success in steering policy away from more aggressive tariff measures and controversial Federal Reserve appointments has bolstered his reputation, but bond markets are less susceptible to political pressure than domestic legislative bodies.
The political constraints facing the Treasury Secretary are significant. President Trump remains resistant to any form of genuine austerity, recognizing that American voters are unlikely to support substantial reductions in public spending or increases in taxation. Consequently, Bessent is caught between the need to maintain market confidence and the imperative to adhere to the administration’s populist spending commitments. This tension limits his ability to implement textbook solutions for budget consolidation, which typically involve disciplined fiscal restraint.
Historical data suggests that the recent rise in interest rates is likely to persist, making the strategy of waiting out a spike in long-term yields increasingly risky. Many prominent economists who previously predicted permanently low rates are now reconsidering their positions, acknowledging that higher borrowing costs may become the new normal. For the United States, with its massive debt burden and aging population requiring increased support, the window for pain-free fiscal adjustment appears to be closing.
The implications of these developments extend beyond immediate market reactions. If budget pressures continue to mount without corresponding revenue growth or spending discipline, the result could be a rapid erosion of trust in US financial instruments. This scenario would not only increase borrowing costs for the federal government but also affect households and businesses that rely on stable credit conditions. The coming months will likely reveal whether Bessent’s tactical shifts can mitigate these risks or if they merely delay inevitable confrontations with fiscal reality.
As the administration navigates this precarious landscape, the focus remains on balancing short-term political demands with long-term economic stability. The success of Bessent’s approach will depend largely on whether AI-led growth materializes as quickly and robustly as projected. Until then, the combination of high deficits, rising rates, and shifting global capital flows presents a formidable challenge to US fiscal policy.
Market participants are closely watching for signs of further intervention or retreat from current strategies. The absence of clear signals regarding future tax policy or spending caps leaves investors uncertain about the trajectory of US debt management. This uncertainty, coupled with the broader global economic environment, underscores the fragility of the current fiscal position and the high stakes involved in maintaining confidence in American financial leadership.
Sources behind this briefing
Go to the original reporting
- The Guardian US Politics↗Is the Trump Treasury panicking over the level of US debt?