The short version
- President Santiago Peña was impeached and placed under house arrest following the insolvency of Ueno Bank, a digital lender with deep ties to his administration.
- Approximately three million Paraguayans had their accounts frozen overnight, causing severe economic disruption including halted salaries for media workers and suspended pension payments.
- Investigators are examining allegations that state funds were improperly invested in the bank and that regulatory rules were relaxed to benefit the institution while Peña held shares in its parent company.
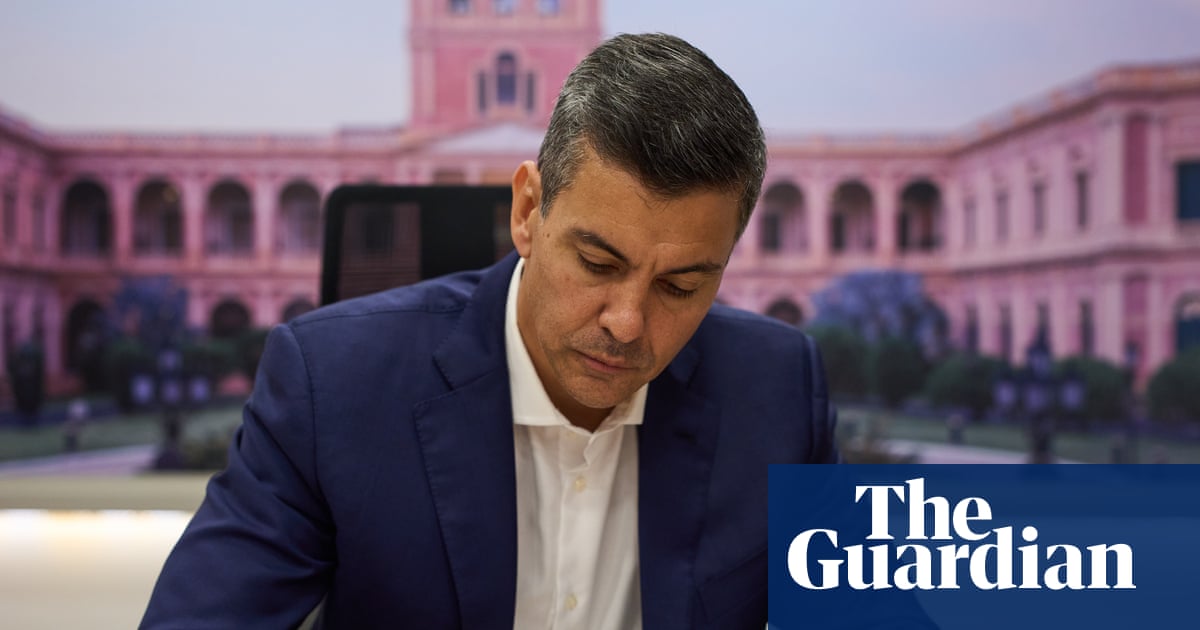
A sudden financial collapse has upended Paraguay’s political landscape, resulting in the impeachment and house arrest of President Santiago Peña. The crisis centers on Ueno Bank, a digital lender that rapidly expanded across the nation before regulators declared it insolvent. Within days, the situation escalated from a banking emergency to a constitutional rupture, stripping Peña of his presidency and subjecting him to criminal proceedings in ordinary courts after lawmakers revoked the special jurisdiction he sought by resigning.
The immediate impact on the public has been severe. Nearly three million Paraguayans, representing roughly sixty percent of the adult population, found their accounts frozen overnight when the central bank ordered Ueno into resolution. For many, this meant an inability to view balances or access funds just after payday. The disruption has rippled through the economy, with businesses reporting sales drops of up to eighty percent as consumers faced sudden liquidity constraints. Ordinary citizens are struggling to cover basic expenses, highlighting the vulnerability of a population heavily reliant on digital financial services.
Ueno Bank had become deeply embedded in Paraguayan society and commerce before its fall. It sponsored major sports entities, including the national football team and top clubs, and served as the primary bank for a vast share of the population. The institution’s collapse also paralyzed media operations linked to its parent group, suspending salaries for hundreds of workers and halting payments for thousands of pensioners whose public funds were invested in the lender. Analysts note that the widespread nature of the bank’s reach turned a financial failure into a broad social emergency.
The political fallout has been swift and decisive. Peña, who took office in 2023 promising to restore national prosperity and attract foreign investment, faced mounting pressure from opposition lawmakers and mass protests. Congress moved to impeach him as a measure to prevent further social unrest. Despite his attempt to resign to retain the status of a senator for life, which would have granted immunity from ordinary criminal courts, legislators stripped him of that position. He now faces investigation by the public prosecutor’s office.
Central to the inquiry is the relationship between Peña’s administration and Ueno Bank. Shortly after assuming office, Peña appointed Carlos Carvallo Spalding, formerly the bank’s chief executive, to lead the central bank. Under Spalding’s oversight, regulatory changes allowed Ueno to transition from a finance company to a fully licensed digital bank within months. Critics argue that this rapid approval and subsequent regulatory relaxation favored the institution disproportionately.
Investigations are also examining Peña’s personal financial ties to the conglomerate. Records indicate he purchased shares in a company that later became part of Ueno Holding, the parent entity controlling the bank, before taking office. He retained these shares until April 2025, well into his presidency, claiming they were held purely as an investor. The public prosecutor is probing allegations of illicit enrichment and favoritism, particularly regarding how state and pension funds were directed toward the lender.
An estimated eight hundred to eighty-six million dollars in public and pension funds were invested in Ueno during Peña’s term. Internal reports from the central bank had previously flagged irregularities, including loans issued to companies within the same corporate group, but these warnings were dismissed by the administration as a media campaign. The revelation of these documents has intensified scrutiny over whether regulatory oversight was compromised to protect the bank’s interests.
The legal consequences are expanding beyond the presidency. Spalding resigned and was subsequently ordered arrested, joining Peña under house arrest. Police have also detained eight senior executives and directors of Ueno and its controlling group on suspicion of concealing the bank’s deteriorating financial health for months. As the central bank manages the resolution process, the focus remains on stabilizing the banking system and determining accountability for the systemic failures that led to the crisis.
The events in Paraguay underscore the risks associated with rapid digital financial expansion without robust regulatory safeguards. The intertwining of political power, regulatory authority, and private financial interests has created a complex web of liability. With millions still waiting for access to their funds and the government in transition, the country faces an uncertain period of economic recovery and legal reckoning.
Observers note that the speed of the collapse suggests long-standing structural issues were masked by aggressive marketing and political protection. The removal of Peña marks a significant shift in Latin American politics, where he had been viewed as a key ally for conservative movements and international investors. The coming months will likely see intense legal battles and efforts to restore public trust in both the banking sector and democratic institutions.
Sources behind this briefing
Go to the original reporting
- The Guardian US↗‘Very strange, very sad’: Paraguay bank collapse fells a presidency and leaves millions broke