The short version
- Chair Kevin Warsh declared an end to forward guidance, stating the Fed's primary mandate is delivering stable prices rather than signaling future rate moves.
- Markets interpreted his comments as a potential precursor to interest rate increases, despite the central bank holding rates steady at its July meeting.
- The speech highlights growing tension between the Federal Reserve and the White House, which continues to advocate for lower borrowing costs.
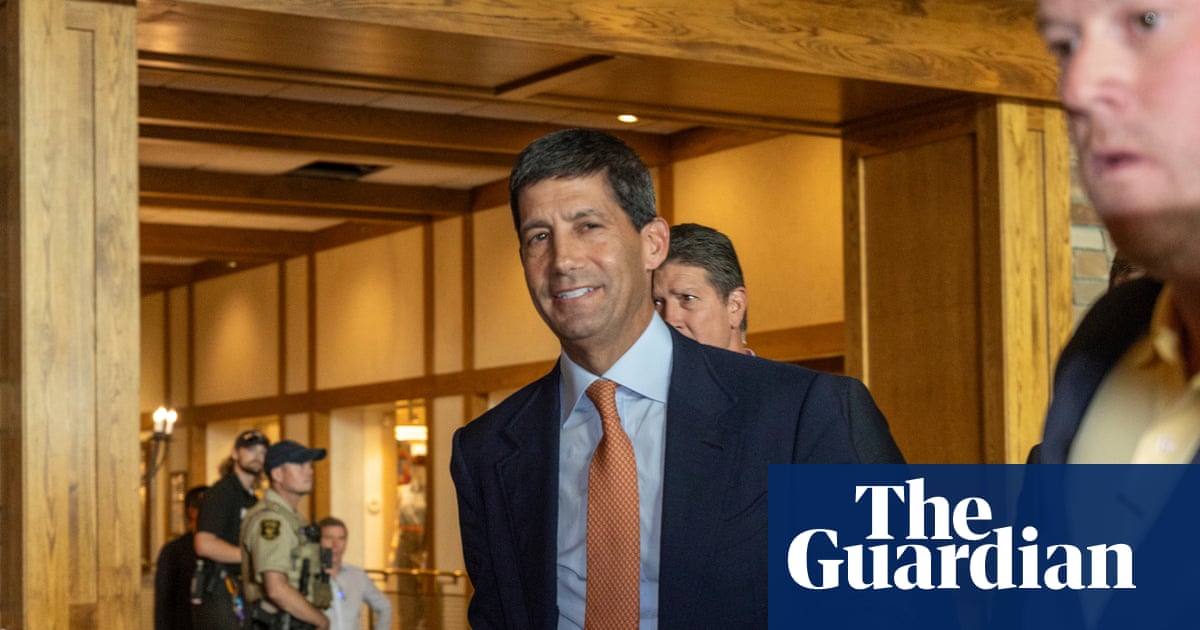
Kevin Warsh, the chair of the US Federal Reserve, used his inaugural major address at the Jackson Hole symposium to redefine the central bank’s communication strategy. Speaking in Wyoming on Friday, Warsh declared that the era of forward guidance is over, arguing that such practices were emergency measures adopted during the 2008 financial crisis and have since overstayed their welcome. By explicitly rejecting the tradition of hinting at future policy directions, Warsh signaled a departure from the approach taken by his predecessor, Jerome Powell, who used similar platforms to foreshadow rate adjustments.
The core message of Warsh’s speech centered on the Fed’s commitment to price stability. He emphasized that delivering stable prices remains the institution’s fundamental job, even as inflation remains stubbornly above the 2% target. While acknowledging that recent economic data showed resilience in both consumer and corporate sectors, Warsh cautioned that underlying inflationary trends had not meaningfully improved. He described progress on curbing price growth over the past few years as modest, suggesting that the central bank cannot yet declare victory against persistent cost pressures.
Financial markets reacted swiftly to the absence of dovish signals. Although Warsh did not explicitly state whether interest rates would rise in the coming months, investors interpreted his focus on inflation control as a warning that tightening measures could be imminent. This perception led to a slight increase in yields for two-year and 10-year US Treasury notes, while the S&P 500 remained largely flat and the Dow Jones Industrial Average dipped slightly. The bond market’s sensitivity to inflation fears has been heightened recently, with 10-year note yields reaching their highest levels since 2007.
The current interest rate environment remains a point of contention within the Federal Reserve itself. At the most recent board meeting in July, a majority of voting members opted to keep rates steady at a range of 3.5% to 3.75%. However, this decision was not unanimous; three out of twelve voting members dissented, advocating for a quarter-percentage-point increase. This level of internal disagreement marks the first time in a decade that so many board members have publicly opposed the prevailing policy stance, indicating deep uncertainty about the appropriate path forward.
Warsh’s stance places him at odds with President Donald Trump, who has aggressively called for interest rate cuts to stimulate economic activity. The White House continues to argue that lower borrowing costs are necessary, despite warnings from economists that such moves could exacerbate existing inflationary pressures. Warsh has faced the delicate task of managing an economy shaken by higher oil prices linked to the war in Iran while resisting political pressure to ease monetary policy. His refusal to provide forward guidance may be an attempt to insulate the Fed from external expectations and maintain independence.
Inflation data presents a mixed picture that complicates policy decisions. After hitting a three-year high of 4.2% in May, US inflation cooled to 3.4% in July. While this figure is better than some forecasts predicted, it remains approximately 1% higher than levels seen the previous year. Warsh noted that while summer price readings were favorable, they did not indicate a fundamental shift in underlying economic trends. The persistence of elevated prices suggests that the Fed must remain vigilant against premature easing.
The broader macroeconomic landscape adds further complexity to the Fed’s mandate. The US gross national debt recently surpassed $40 trillion for the first time in history, raising concerns about long-term fiscal sustainability. Additionally, rising US interest rates have had spillover effects globally, driving bond yields in the UK, Germany, France, and Japan to their highest levels in decades. A recent announcement by the US Treasury regarding a massive debt buy-back scheme provided only temporary relief to bond markets, underscoring the fragility of current financial conditions.
Looking ahead, market participants will likely scrutinize every word from Warsh for clues about future policy moves, even as he denies providing them. The Jackson Hole symposium has traditionally served as a key indicator of the Fed’s direction, but Warsh’s rejection of forward guidance means investors must rely more heavily on economic data and internal board dynamics. With inflation remaining above target and political pressures mounting, the Federal Reserve faces a challenging path in balancing price stability with economic growth.
The implications of Warsh’s new communication style extend beyond immediate market reactions. By ending the practice of signaling future rate changes, the Fed may introduce greater volatility into financial markets as investors lose a predictable source of policy insight. This shift could force traders and analysts to develop new models for anticipating monetary policy decisions, relying less on verbal cues and more on real-time economic indicators. The coming months will test whether this approach can maintain market confidence while the Fed continues its fight against inflation.
Sources behind this briefing
Go to the original reporting
- The Guardian US Politics↗Fed chair addresses inflation and says central bank’s job is ‘to deliver stable prices’