The short version
- Ryanair CEO Michael O’Leary predicts European airfares may rise by 10% to 20% next year due to soaring fuel costs and limited hedging.
- Most carriers lack significant fuel price protection for late 2027, exposing them to spot rates that have doubled recent contract prices.
- Airlines are responding with schedule reductions and route cuts, while industry leaders warn of potential bankruptcies among less capitalized competitors.
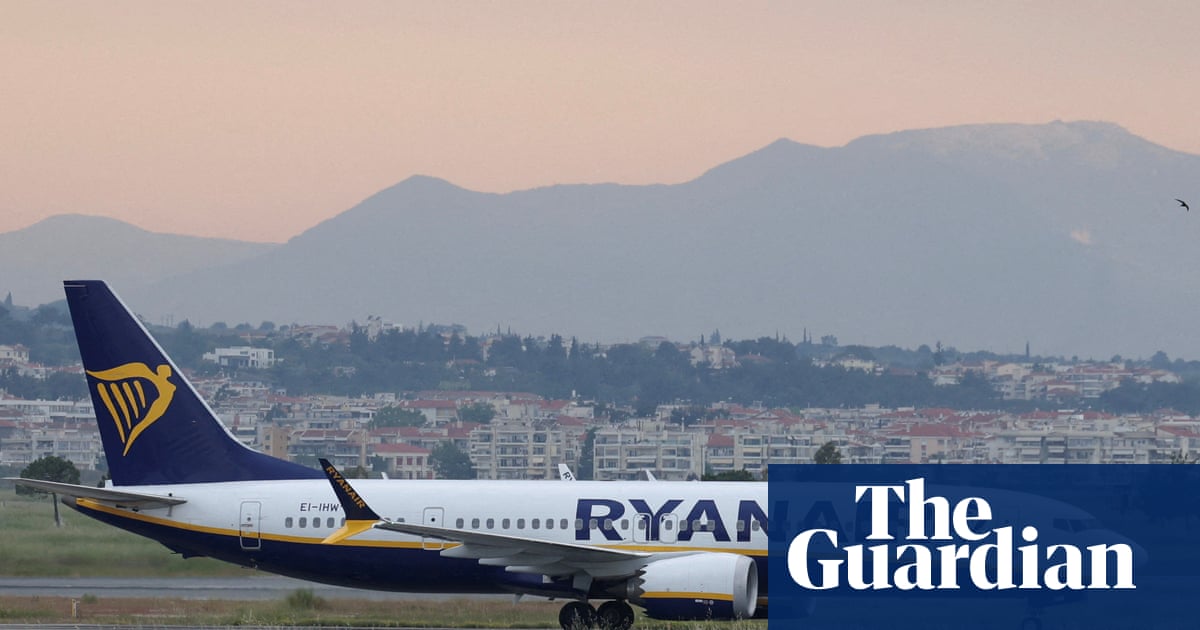
The European aviation sector is bracing for a significant financial shock in the coming year, driven by escalating jet fuel costs linked to ongoing conflicts in the Middle East. Michael O’Leary, chief executive of Ryanair, recently projected that airfares across Europe could surge by as much as 20% in 2027, marking what he described as the largest price increase in the region’s history. This forecast stems from a combination of geopolitical instability disrupting fuel supplies and a widespread lack of financial hedging among carriers for the latter half of next year.
Jet fuel represents a substantial portion of operating expenses for airlines, and prices have climbed sharply in recent months. The International Air Transport Association had previously estimated that jet fuel costs would average $152 per barrel in 2026, a significant jump from the $90 average seen in 2025. This increase threatens to erode profit margins across the industry. O’Leary noted that while many airlines managed to secure hedges for 2026, protection for 2027 is largely absent, leaving carriers vulnerable to volatile spot market rates.
Ryanair’s own hedging strategy illustrates this exposure. The airline had secured contracts covering 80% of its fuel needs at $67 per barrel when the conflict in Iran began earlier in the year. However, for 2027, Ryanair is approximately 85% unhedged. The small portion of fuel costs covered by contracts for next year was locked in at $85 per barrel, a figure that stands in stark contrast to current spot rates, which have hovered near double that amount. O’Leary indicated that most other European carriers face a similar lack of protection.
The financial strain is already prompting operational adjustments across the industry. EasyJet reported a £105 million annual increase in fuel costs earlier this year. To mitigate expenses, the carrier has hedged only 62% of its fuel requirements for the first half of 2027 and just 37% for the second half. In October, EasyJet announced it would remove 700,000 seats from its winter schedule as a direct measure to conserve fuel and reduce costs.
Ryanair has also taken decisive action to curb expenses, particularly in markets with unfavorable regulatory changes. During a conference in Brussels, O’Leary revealed plans to cut 20 routes and more than one million seats from the airline’s Belgian operations for the winter season. This reduction follows a decision by the Belgian federal government to raise its aviation tax from €2 to €7 per passenger starting in January. The move underscores how regulatory pressures compound the challenges posed by rising fuel prices.
Industry leaders have expressed concern that the current cost environment could lead to structural changes within European aviation. O’Leary warned that the combination of high fuel bills and insufficient hedging could result in bankruptcies and takeovers among weaker carriers. The lack of price protection means that airlines will be forced to absorb higher costs or pass them on to consumers, with many executives anticipating a period of consolidation as smaller players struggle to survive.
Consumer behavior remains a critical variable in this equation. Surveys indicate that travelers are aware of the impending fare increases and have expressed a willingness to pay more for flights. However, airlines remain uncertain about the durability of this willingness. There is no clear indication of how long passengers will tolerate higher prices before demand begins to soften, adding another layer of risk to revenue projections.
The outlook for 2027 suggests a difficult period for both airlines and consumers. With fuel prices expected to remain elevated due to geopolitical tensions, and with limited hedging in place, carriers face a precarious financial position. The industry’s response will likely involve continued schedule reductions, potential mergers, and sustained fare increases, reshaping the competitive landscape of European air travel.
As airlines navigate these challenges, the focus shifts to how quickly they can adapt their business models to withstand prolonged cost pressures. The expiration of existing hedges and the rise in spot prices create a narrow window for strategic maneuvering. Investors and analysts will be watching closely to see which carriers can maintain profitability without sacrificing market share or operational integrity.
The broader implications extend beyond individual airlines, affecting travel patterns and economic activity across Europe. Higher fares could dampen tourism and business travel, while industry consolidation may reduce competition in certain routes. The coming months will test the resilience of European aviation as it confronts one of its most significant cost shocks in recent memory.
Sources behind this briefing
Go to the original reporting
- The Guardian World↗European air fares could rise by as much as 20% in 2027, Ryanair boss predicts