The short version
- The head of the EU Chamber of Commerce in China warns that European manufacturers may abandon competition with Chinese firms by the end of the decade if current trends persist.
- Eskelund suggests a strategic pivot where European companies integrate into Chinese supply chains rather than treating Beijing as an adversary, citing risks of mass unemployment and tax base erosion.
- German industries, particularly automotive and chemicals, are already experiencing significant pressure from reduced profits in China and increased domestic competition from subsidized Chinese exporters.
Jens Eskelund, the head of the European Union Chamber of Commerce in China, has issued a stark warning regarding the future of European manufacturing. He suggests that by the end of this decade, many European firms may cease attempting to compete directly with their Chinese counterparts. This potential shift is driven by growing fears of widespread job losses and structural economic damage if current trade dynamics continue unchecked. Eskelund frames this not as a sudden surprise but as the logical conclusion of long-standing industrial policies in Beijing.
The core of Eskelund’s argument involves a fundamental rethinking of Europe’s relationship with Chinese industry. He proposes that European companies should consider becoming part of Chinese supply chains rather than viewing them solely as competitors. This approach, described as moving from 'Made in China for China' to 'Made in China for the world,' aims to preserve value creation for both sides. Eskelund argues that if trade begins to destroy value for one party while benefiting the other, nations will inevitably question the utility of international commerce altogether.
Economic forecasts support the urgency of this concern. A report by Goldman Sachs indicates that Chinese exports could reduce the European Union’s gross domestic product by 0.5 percent by 2030. The impact on Germany, Europe’s largest economy, is projected to be even more severe, with a potential GDP reduction of up to 0.9 percent. These figures highlight the tangible risks associated with maintaining a purely competitive stance against a state-backed industrial powerhouse that has systematically reduced its own import dependencies over the past three decades.
The automotive sector serves as a primary example of these pressures. German carmakers are facing a dual challenge: declining profits in the Chinese market and intense competition at home from manufacturers like BYD, Geely, and SAIC Motor. BMW recently reported a 22 percent drop in sales in China during the first nine months of the year, aligning with expectations of suppressed domestic demand there. The company also issued its second profit warning for the year, illustrating the immediate financial strain on established European brands.
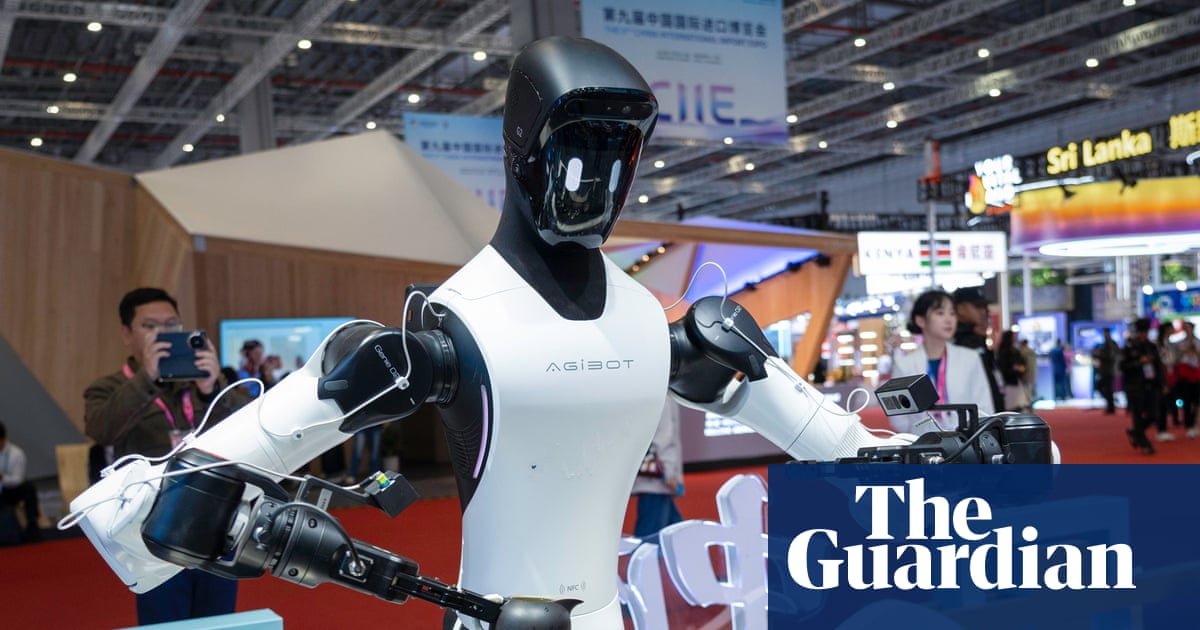
Eskelund rejects the term 'China shock 2.0' to describe this influx of exports, arguing that the situation should not be surprising. He points out that Beijing’s strategy to displace imports has been a consistent theme in its five-year plans since the 'Made in China' initiative was launched in 2015. The latest plan, covering 2026 to 2030, doubles down on self-reliance and targets specific high-tech sectors for dominance. These include artificial intelligence, quantum computing, robotics, smart green technology, biomanufacturing, brain-computer interfaces, and 6G communications.
The mechanism behind China’s industrial expansion is highly coordinated. Once strategic goals are set in Beijing, incentives, tax breaks, and subsidies flow down to regional and local levels. This ensures that officials across the country understand their priorities and execute them with precision. Eskelund advises European industries not to hide from this reality but to brace for delivery. He emphasizes that China’s focus on outcomes contrasts sharply with Europe’s traditional emphasis on principles, raising questions about whether adherence to abstract ideals is yielding undesirable economic results.
A recent report by the Centre for European Reform urged Germany to stop admiring Beijing and adjust its strategy accordingly. The report noted that China remains committed to displacing imports in sectors where it still relies on foreign supply. This includes advanced chips, solar panels, wind turbines, robots, and driverless cars. The implication is that Europe’s window to negotiate favorable terms may be closing as China solidifies its position in these critical industries.
Eskelund is currently engaged in discussions with European Commission officials in Brussels, providing feedback from Beijing. He warns that creating new dependencies could result in Europe losing the ability to determine its own future. The potential consequences include fraying communities, multigenerational unemployment, and spiraling social benefit costs. His advice to EU leaders is to engage with China to find a point where value creation is mutual. Without such a shift, he suggests that European manufacturing faces an existential crossroads that could redefine the continent’s economic landscape.
The broader significance of this warning lies in the potential for mass job losses and the collapse of tax bases in key industrial regions. If manufacturing disappears from European countries, the social and economic fallout could be severe. Eskelund’s perspective challenges the prevailing mood of protectionism in Brussels, Berlin, and Paris. He argues that a fundamental shift in approach is necessary to avoid a doomsday scenario where trade no longer serves the interests of European nations.
As Europe navigates this inflection point, the debate over how to handle Chinese competition intensifies. The record trade deficit, currently running at approximately 1.18 billion euros per day, underscores the scale of the challenge. Eskelund’s call for integration rather than isolation offers a controversial but pragmatic alternative to outright decoupling. Whether EU leaders will adopt this strategy remains uncertain, but the stakes for European industry and employment are undeniably high.
Sources behind this briefing
Go to the original reporting
- The Guardian US↗EU manufacturers could give up on competing with China by 2030, warns commerce chief