The short version
- Apple reported a 12% increase in revenue to $30.71 billion for the July-September period, beating analyst expectations.
- CEO John Ternus cited an unprecedented rise in memory chip prices due to competition with AI datacenters, predicting further cost increases.
- The company raised prices on iPads, MacBooks, and iPhones to offset some margin pressure, while shares fell slightly in after-hours trading.
Apple Inc. delivered a stronger-than-anticipated financial performance for its fiscal third quarter, reporting revenue of $30.71 billion, a twelve percent increase from the same period last year. This result defied a broader downward trend observed among major technology peers during the same timeframe, including disappointing quarterly reports from Alphabet, Amazon, and Intel. The earnings per share reached $2.10, surpassing the average analyst expectation of $1.99 on revenue of $113.4 billion as polled by FactSet. The company noted that these figures included a five-cent-per-share benefit derived from tariff refunds.
Despite the robust top-line growth, Apple’s leadership issued a stark warning regarding supply chain pressures. John Ternus, who assumed the role of chief executive officer in September, described the current environment for memory chip pricing as unprecedented during a conference call with investors. He indicated that costs for these critical components are expected to rise even further in the fourth quarter compared to the previous three months. This surge in component costs is largely attributed to intense competition between consumer electronics manufacturers and datacenters building infrastructure for artificial intelligence applications.
The tech industry has been grappling with what some observers have termed a crisis in memory availability, driven by surging demand from AI-focused datacenters. This scarcity has pushed prices upward, creating significant headwinds for hardware makers. Ternus explained that Apple had taken preemptive measures to mitigate the impact on profit margins by increasing prices across several product lines. Specifically, price hikes were implemented for iPads and MacBooks in June, followed by adjustments to iPhone pricing in September. These moves provided some financial offset against the rising input costs.
Investor reaction to the earnings report was mixed, with Apple’s shares declining by 2.75 percent in after-hours trading on Wall Street. The drop suggests that while revenue exceeded expectations, concerns about future margin compression due to memory chip inflation remain prominent. Ben Barringer, head of technology research at Quilter Cheviot, characterized the results as acceptable but leaning toward the disappointing side. He noted that while overall revenue growth was driven by strong iPhone sales and robust performance in China, other segments such as iPads and wearables underperformed relative to the group average.
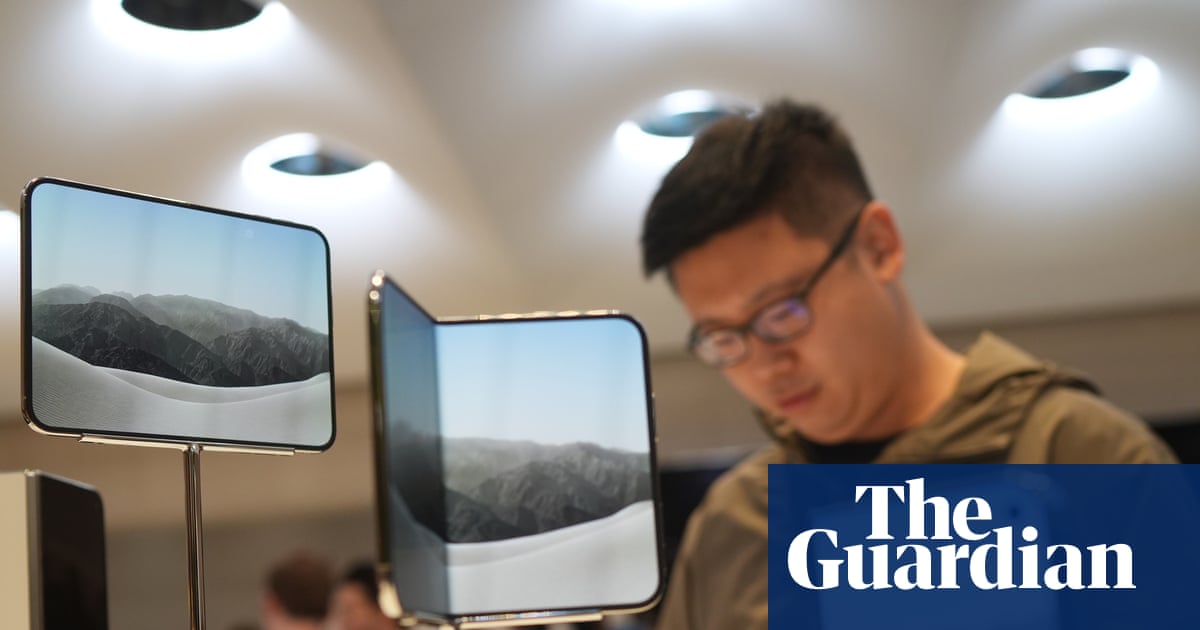
The services segment showed growth of ten percent, which Barringer described as lower than the company’s typical performance standards. However, he highlighted positive momentum in specific hardware categories, particularly the Mac Mini, which has seen strong sales due to its utility in running agentic AI applications. There is also emerging interest in the iPhone Duo, although Barringer cautioned that it is still early days for this product as it has not yet reached full release. He suggested that if successful, the new device could help drive the next phase of innovation for the company.
Analysts pointed to Apple’s strategic positioning as a key factor in its resilience. Jacob Bourne, an analyst at Emarketer, emphasized that record iPhone revenue and strong growth in the Chinese market demonstrated the durability of Apple’s business model. Unlike some competitors who are facing investor uncertainty regarding massive capital expenditures on AI infrastructure, Apple has maintained a more conservative approach to such spending. This tepid strategy toward heavy AI infrastructure investment has helped preserve cash flow, allowing the company to avoid the financial risks associated with the aggressive build-outs seen elsewhere in the sector.
Apple’s ability to partner with other technology firms, such as Alphabet, may further strengthen its artificial intelligence capabilities without requiring direct, large-scale capital outlays. This collaborative approach allows Apple to integrate advanced AI features into its ecosystem while managing cost structures more effectively than peers who are building their own datacenter capacity from the ground up. As Ternus navigates his first full quarter as CEO, the balance between maintaining premium pricing power and managing supply chain volatility will likely remain a central focus for investors.
Looking ahead, the company faces continued pressure from memory chip markets that show no immediate signs of stabilizing. The competition for semiconductor resources between consumer electronics and AI infrastructure is expected to persist, potentially keeping input costs elevated through the remainder of the year. Apple’s strategy of passing some of these costs to consumers through price increases has provided a buffer so far, but the long-term sustainability of this approach depends on maintaining strong demand despite higher prices. The upcoming release of new products, including the fully launched iPhone Duo, will be critical in sustaining revenue momentum.
The broader implications of Apple’s performance highlight a shifting dynamic in the technology sector. While many firms are struggling with the high costs of AI adoption, Apple’s focus on hardware sales and strategic partnerships offers a different path forward. The company’s strong showing in China also underscores the importance of international markets in offsetting domestic or global supply chain challenges. As the fiscal year progresses, investors will be watching closely to see how effectively Apple can manage these competing pressures while continuing to innovate in an increasingly competitive landscape.
Ultimately, the third-quarter results provide a snapshot of a company navigating complex economic and technological headwinds. The combination of strong revenue growth, strategic pricing adjustments, and cautious capital allocation has allowed Apple to outperform many of its peers despite significant cost inflation in key components. However, the warning from CEO John Ternus about unprecedented memory chip prices serves as a reminder that the challenges are far from over. The coming quarters will test whether Apple’s current strategies can withstand sustained pressure from both supply chain constraints and evolving consumer demands.
Sources behind this briefing
Go to the original reporting
- The Guardian US↗Apple warns of ‘unprecedented’ rise in memory chip prices